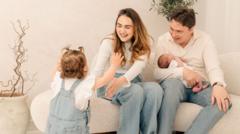
Richard Brain says that opening pensions for his young children means a few financial sacrifices now
ByElizabeth Anderson
Business reporter
Richard and Caitlin Brain’s two children are aged just 20 months and five months respectively, yet mum and dad have already set up pensions for them.
The Brains, who live in Swansea, south Wales, are paying £50 a month into each of their kids’ accounts. It’s money that the children won’t be able to access until they are 57, under current UK private pension fund rules., external
So the eldest will have to wait until 2082, and the youngest until 2083.
Despite the wait, Richard, 30, is convinced that he and Caitlin, 28, are doing the right thing.
“Paying into their pensions means we can play a part in their future far beyond our own years. And the money has decades to grow.”
‘We don’t eat out as often as we used to’
Richard’s financial knowledge is explained by the fact he works for an investment firm. Caitlin is currently on maternity leave from her job working for the local council.
He earns less than £90,000 a year, while she currently doesn’t have an income as she has not yet returned to work after her statutory maternity pay of £194 a week ended.
In addition to their children’s pensions, Richard and Caitlin have also set up Junior ISA savings accounts for them, and pay in £60 a month per child – money the kids will be able to access when they turn 18.
The couple believe this is the best of both worlds – the ISAs could help their children with university costs, starting a business or a house deposit, while the pensions are intended to provide financial security much later in life.
Paying a combined £220 a month into their kids’ funds, in addition to £200 into their own private pensions and savings, the couple say they must live more frugally than in the past.
“We’re not on the breadline, but investing this money does mean doing a little less,” says Richard. “We don’t eat out as often as we used to, which as foodies is a pain.
“And we don’t go as big for one another on birthdays and Christmas so that we can still do it for the kids.”
‘I want to retire earlier so this will help’
Pensions for children, also called Junior self-invested personal pensions (SIPPs), were introduced in the UK in 2001. You can pay in a maximum of £2,880 per year, which the government will then top up with £720 tax relief to make a total £3,600.
The popularity of Junior SIPPs has grown, industry figures show.
One provider, Hargreaves Lansdown, says that in the 12 months to April 2026 it had seen two and a half times as many accounts open, external as in the same period a year earlier.
Another, Fidelity, says it has seen the number of accounts more than triple since December 2023.
While giving their kids a pensions head start is a powerful incentive for some parents, how do the children themselves feel about not being able to touch the money for potentially 50 years or more?
Fifteen-year-old Hugo Thompson from Manchester seems unfazed. His parents, who work in finance, have been paying the maximum amount into his Junior SIPP for the past 10 years.
“The money invested means perhaps I’ll be ahead when I’m older,” he says. “So I won’t have to put quite so much of my own money in! I want to retire earlier than the state pension age so this will all help.”
Hugo’s mother Annabel, who works in finance, also saves into a Junior ISA for him, but says she still also invests into her own pension and savings. “For me, Junior SIPPs should only be considered once you feel you have enough money of your own,” she says.
Hugo Thompson is happy to wait until he is at least 57 to access the pension fund
For parents who can afford it, the money can grow substantially before the child can access it, says Jemma Slingo, a pensions specialist at Fidelity.
“Paying in £50 a month from birth, including tax relief, the family would contribute £10,800 over those 18 years. The pot could grow to around £135,000 by retirement. That’s the real power of starting early – relatively modest amounts can have an exceptionally long time to compound.”
It’s not just British parents that are opening long-term investments for their children.
In July this year, US President Donald Trump launched a new retirement investment scheme for children called Trump Accounts.
Families, friends and employers can contribute up to $5,000 (£3,800) per year per child. The difference with the UK is that the children can access the funds from when they turn 18, although withdrawals are subject to taxes and a possible 10% penalty if made before the age of 59 and a half.
Wally Luckeydoo, a personal finance teacher at Smyrna High School in Tennessee, has opened Trump Accounts for his two children, aged four and three.
Wally Luckeydoo says he is giving his children a “financial head start”
“My dad passed away when I was very young, and my mom did everything she could to provide for us, often with just the bare minimum,” says Wally.
“For much of my adult life, I have felt like I was trying to catch up financially, particularly because of significant student loan debt.
“I don’t necessarily think of this as specifically saving for my kids’ retirement. I think of it as giving them a head start and helping change the trajectory of our family financially.”