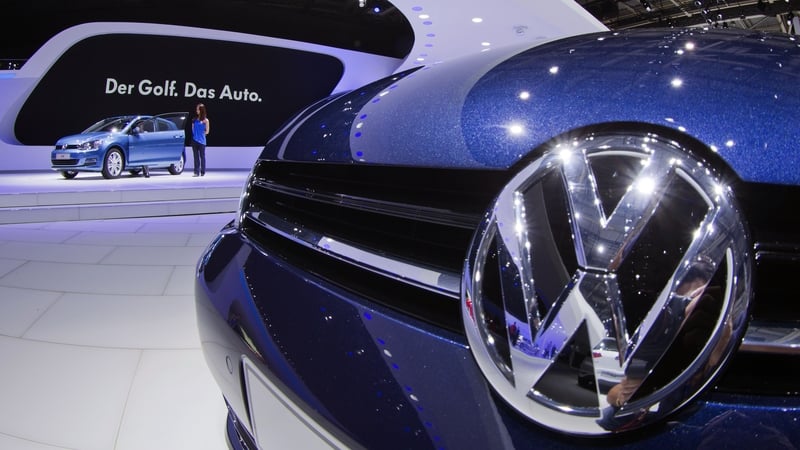
Volkswagen has slashed its outlook today, flagging €10 billion in one-off items related to its stake in luxury sportscar maker Porsche, provisions for job cuts and a weak Chinese market.
The profit warning deepens a crisis at the world’s second-largest automaker, which earlier this month managed to agree far-reaching cuts with unions in the face of fierce competition from Asian rivals, US tariffs and stagnant demand in Europe.
Shares in Volkswagen, the world’s second-largest automaker, closed 5.6% lower on the announcement, while Porsche’s stock fell 3.3%. Volkswagen’s top shareholder Porsche also cut its outlook, sending its shares 4.9% lower.
New mid-term assumptions for Porsche, of which Volkswagen owns 75.4%, led to an impairment of some €6 billion, it said.
The German-based group, which also includes the Audi, Skoda and Seat brands among others, now expects a profit margin of 1% at the most in 2026, having previously guided for 4.0% to 5.5%.
The automaker warned of a “further deterioration in the market environment, especially in China, as well as an accelerated shift in demand in favour of battery-electric vehicles”.
This, it said, would lead to lower expectations for the Audi and Volkswagen passenger car brands.